
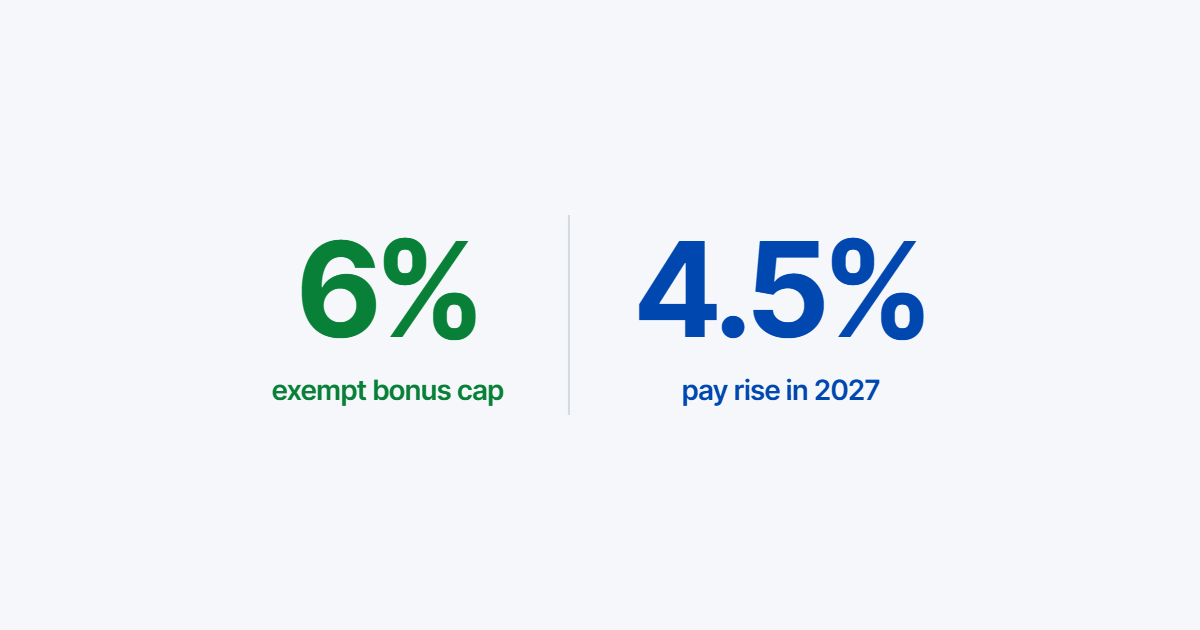
Portugal’s 2027 State Budget proposal, still under discussion in Parliament, keeps the exemption from income tax (IRS) and social security contributions for productivity and performance bonuses, profit-sharing and year-end bonuses, of up to 6% of each employee’s annual base salary. The scheme has been in place since 2025 and was renewed in 2026.
What stays the same
Bonuses must be paid voluntarily and not on a regular basis. When the conditions are met, they are exempt from income tax and fall outside the base for social security contributions, for both the employee and the company. In the annual income statement given to the employee, the company must state that the conditions were met.
The main condition: a pay rise
The exemption only applies if the company makes an eligible pay rise in 2027. The proposed reference is 4.5%, after 4.6% in 2026 and 4.7% in 2025. What counts is the company’s average salary, but also the rise for those earning up to that average.
There are specific rules for these calculations, and compliance depends on the salaries paid over the whole year. A bonus paid mid-year may depend on pay rises that have not been made yet.
Planning ahead
That is why decisions on 2027 pay rises should be made early, ideally before January. The same pay rise may also give access to a corporate tax (IRC) incentive, which has its own conditions. The proposal may still change before the final vote, scheduled for 24 November.
Guiding these decisions throughout the year is part of our work with every client. Talk to us or book an exploratory meeting.
Sources: 2027 State Budget Bill; Law no. 73-A/2025 (2026 State Budget), article 96; Tax Benefits Statute (EBF), article 19-B.