
Anyone starting a business in Portugal has to decide early on how to operate: as a sole trader (empresário em nome individual) or through a company, such as a single-member private limited company (sociedade unipessoal por quotas). The choice may look like a formality, but it has practical effects on taxes, personal risk and day-to-day administration.
Who is liable for the debts
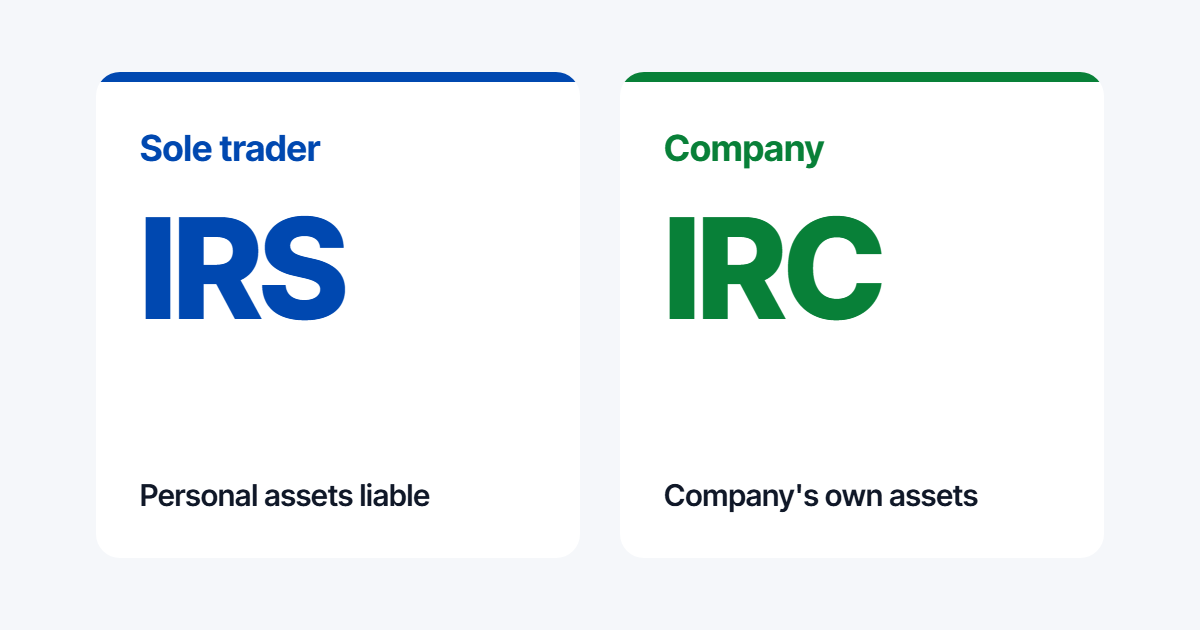
A sole trader has no assets separate from the business. If the business runs into debt, the owner’s personal assets are liable for it.
A company, even with a single shareholder, has its own assets. As a rule, it is the company’s assets, not the shareholder’s, that answer to creditors. There are exceptions, for example when the shareholder gives a bank a personal guarantee.
Taxes and accounting
For a sole trader, business income is taxed under personal income tax (IRS), together with the owner’s other income. Up to €200,000 of annual income, the simplified regime may apply, with its own rules; above that, or by choice, tax is based on full accounts.
A company pays corporate tax (IRC) on its profit and must always keep full accounts, with a certified accountant. What later reaches the shareholder, as salary or distributed profits, is taxed separately.
A decision for the years ahead
No single form is best for everyone. Think of a designer starting out alone, with few costs and no employees: the simplest option may work well at first. If she plans to hire staff, invest in equipment or take on larger contracts, the answer may change.
Expected turnover, costs, business risk and growth plans all matter. Changing form later is possible, but it involves its own procedures and costs, so an informed decision from the start pays off.
Guiding these decisions throughout the year is part of our work with every client. Talk to us or book an exploratory meeting.
Sources: Personal Income Tax Code (CIRS), article 28 (simplified regime and full accounts); Corporate Income Tax Code (CIRC), article 123 (accounting obligations); Commercial Companies Code (CSC), articles 197 and 270-A ff. (private limited and single-member companies).